Tampa vs Nashville Cost of Living
Tampa vs Nashville cost of living is not a one-number comparison. Housing, taxes, insurance, transportation, and the kind of property you choose can change the answer by far more than groceries or gas. In general, headline costs may look similar, but Tampa insurance, flood exposure, association or CDD costs, and Nashville’s inland storm and commute patterns produce different budgets. The useful question is not simply which city is cheaper. It is what your same income and housing budget would let you do differently.
Last updated: September 19, 2026
This comparison uses the latest available public benchmarks, including U.S. Bureau of Economic Analysis regional price data, U.S. Census Bureau housing data, and current state tax guidance. It is a planning guide, not a promise about a particular home or household. I’m Harley Pope with Pope Real Estate Group at The Baker Brokerage, and I help people compare Nashville with the surrounding Middle Tennessee communities where their budget, commute, and everyday priorities may fit better.
Tampa vs Nashville cost of living at a glance
Tampa Bay and Nashville are both fast-changing Sun Belt regions with strong suburban growth. Florida and Tennessee also share the absence of a broad wage income tax. The useful comparison therefore moves quickly to neighborhood, property tax, insurance, flood and storm exposure, association costs, and commute.
| Cost question | Tampa | Nashville and Middle Tennessee |
|---|---|---|
| Housing | Coastal metro with condos, planned communities, and inland suburbs | Inland metro with urban neighborhoods, subdivisions, small towns, and acreage |
| State income tax | Florida does not impose an individual income tax | Tennessee does not tax earned personal income |
| Transportation | Car-centered, with bridges and water shaping routes | Most households should plan around a car |
| Weather-related ownership costs | Hurricane, flood, heat, humidity, roof, and insurance concerns | Storm, hail, wind, drainage, and HVAC condition matter |
| Biggest budget trap | Treating insurance, flood, HOA, or CDD charges as minor details | Assuming every lower-priced suburb produces an easy commute |
The table is directional. Before making a move, compare a real housing payment, a real insurance quote, your tax situation, and your likely weekly driving. That is more reliable than applying one national cost-of-living percentage to every household.
Housing is where the comparison usually becomes real
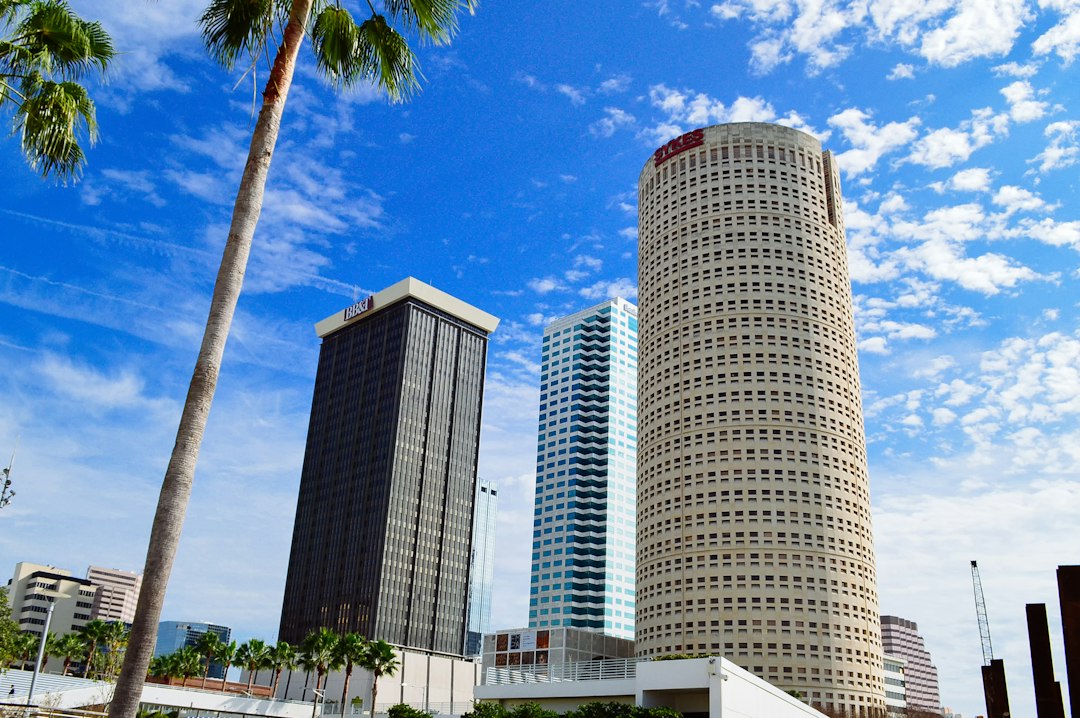
Tampa Bay housing ranges from condos and established city neighborhoods to large planned communities and inland suburbs. Water, evacuation zones, flood maps, building age, association finances, and community development district charges can all affect the payment and risk.
Nashville’s inland market removes coastal storm surge, but not weather risk. Buyers choose among close-in homes, condos, growing suburbs, and rural properties. Hills, creeks, trees, septic systems, and long drives can matter as much as a Florida flood zone.
Do not compare a source-city neighborhood with downtown Nashville and assume you have compared both markets. Nashville is one part of a larger region. Buyers often consider Davidson County, Williamson County, Rutherford County, Sumner County, Wilson County, Cheatham County, Maury County, and Dickson County. Each changes the mix of price, lot size, age, commute, taxes, and services. Start with the Nashville area guide, then use the broader directory of Middle Tennessee communities to compare realistic search zones.
A Tampa seller moving to Tennessee may gain elevation, land, or a different home style. A Nashville buyer could still pay a premium in Franklin, Brentwood, or close-in neighborhoods. Compare the same lifestyle tier, not a waterfront Florida location with a distant Tennessee exurb.
Compare monthly ownership cost, not just purchase price
A lower sale price does not automatically produce a lower monthly cost. The payment should include principal, interest, property taxes, homeowners insurance, mortgage insurance when applicable, association dues, and a realistic maintenance reserve. If the property has a pool, private road, acreage, detached building, older systems, or a septic system, add those costs too.
Tampa due diligence should include flood zone, elevation when relevant, roof age, wind mitigation, homeowners and flood quotes, association reserves, and CDD obligations. Nashville due diligence should include roof and storm history, drainage, trees, HVAC, crawl spaces, and rural systems.
The cleanest exercise is to price three real options on the same day: one home close to Nashville, one farther out with more space, and one that represents the lifestyle upgrade you actually want. Ask a lender for estimated payments using the same down payment and rate assumptions. Then get insurance estimates before treating any option as affordable.
Taxes can change take-home pay, but they are not the whole budget
Florida and Tennessee both lack a broad individual income tax on earned wages. The tax line may therefore be less dramatic than expected. Property taxes, insurance, association charges, utilities, sales taxes, and transportation should drive the comparison.
Tennessee currently has no state income tax on earned income. That may create a meaningful difference for a household coming from a state that taxes wages. The exact benefit depends on income type, deductions, residency timing, and current law, so a CPA should calculate it. Also remember that governments fund services differently. Sales taxes, property taxes, vehicle costs, insurance, and local fees still belong in the comparison.
A useful approach is to build an annual side-by-side worksheet with five lines: state income tax, property tax, insurance, commuting, and housing maintenance. Divide the total by twelve. That monthly number is often more honest than a headline about taxes.
Transportation and commute can erase a housing win
Tampa Bay routes are constrained by water, bridges, and separated job centers. A short distance on the map can turn into a long peak-hour trip, especially when crossing the bay.
Nashville has no bay crossings, but interstates and radial roads concentrate traffic. A home on the wrong side of the city can create the same daily frustration. Choose the commute zone before choosing the house.
For Nashville-area shopping, identify the destinations that will repeat every week, not just the office. Map work, childcare, medical appointments, airport trips, family, worship, recreation, and the grocery store. Then test the routes during the hours you would actually drive. The Nashville neighborhood search guide explains how to organize the search around budget, commute, and home style instead of starting with a long list of place names.
Utilities, climate, and insurance deserve their own line items
Tampa ownership requires planning for hurricanes, wind, flood, roof condition, humidity, mold prevention, pests, and insurance availability. These are not reasons to reject the region, but they must be priced honestly.
Nashville trades tropical coastal risk for thunderstorms, tornado risk, hail, flash flooding, occasional winter ice, pollen, and more tree maintenance. A well-drained lot with a sound roof still deserves a property-specific insurance quote.
In Middle Tennessee, buyers should pay attention to roof age, drainage, grading, trees, HVAC condition, storm exposure, and any mapped flood risk. Utility history can be more useful than a seller’s general description of efficiency. Ask for available bills, review the inspection carefully, and obtain an insurance quote during the contingency period. Never assume two homes with the same price will cost the same to operate.
What daily life feels like after the move
Tampa offers Gulf access, warm winters, boating and beach routines, and a regional lifestyle shaped by water. Nashville offers music and entertainment, hills, lakes, four seasons, and quick transitions from urban neighborhoods to countryside.
The move should answer a life question. Is the goal less storm exposure, a different job network, more land, family proximity, or a new daily rhythm? A lower payment is valuable, but it will not compensate for a location that does not support the reason you moved.
This is where I use what I call The Tuesday Test. Picture a normal Tuesday six months after closing. Where do you wake up? How long does the school or work run take? Can you get to the places you use without turning every errand into a project? Do you have the outdoor space, office, garage, walkability, or privacy you expected? A house should make ordinary days better, not only look impressive during a weekend showing.
How to compare neighborhoods without steering yourself wrong
Choose objective factors before choosing locations. Write down your maximum payment, acceptable drive time, required bedrooms, parking needs, lot preference, tolerance for renovation, and any nonnegotiable property features. If schools matter, use official district boundaries and your own research rather than labels such as “good” or “bad.” If safety matters, review current public data and visit at the times you expect to be there.
Then rank the tradeoffs. A closer-in home may be smaller or older. A newer home may be farther from the destinations you use. More acreage may mean more maintenance or a private wastewater system. A condominium can reduce exterior upkeep but add dues, rules, and financial-document review. There is no universal winner. There is only a better fit for the life and budget you are actually bringing to Tennessee.
A practical relocation plan from Tampa to Nashville
- Set a complete monthly ceiling. Include taxes, insurance, dues, utilities, maintenance, and transportation.
- Choose three search zones. Use one closer-in area, one middle-distance option, and one farther-out value or space option.
- Plan a decision trip. Drive the routes, tour different housing types, and spend time in each area during ordinary hours.
- Prepare financing early. An underwritten preapproval and clear funds plan make the search more useful.
- Quote insurance before committing. Property-specific risk and rebuilding cost matter more than a broad state average.
- Coordinate the move and purchase. Decide whether your current home must sell first, whether temporary housing is acceptable, and how much overlap you can carry.
For broader planning, start with the Middle Tennessee relocation guide. To compare Nashville with other source markets, review the Atlanta comparison, Chicago comparison, and Los Angeles comparison.
For the logistics, use the Tampa Bay-to-Nashville relocation guide. If an agent in Tampa is helping coordinate the move, the Florida Realtor referral process explains how I protect the existing relationship and handle the Middle Tennessee side. You can also review the out-of-state home-buying guide before a decision trip.
Who may prefer Tampa, and who may prefer Nashville?
Tampa may fit someone who wants Gulf access, warm winters, Florida ties, and a coastal-suburban lifestyle and who can price insurance and storm risk comfortably.
Nashville may fit someone seeking an inland market, hills and seasons, different job connections, and access to suburban or rural housing without adding a state tax on wages.
The move may not make sense if it depends on an unrealistic commute, a tax estimate that ignores the rest of the budget, or the assumption that every Nashville suburb is inexpensive. It may make very good sense when it improves both the numbers and the normal week. Great homes make ordinary days better, and that is the standard worth testing.
Frequently asked questions
Is Nashville cheaper than Tampa?
The two metros can overlap substantially. Nashville may reduce some coastal insurance and flood costs, while Tampa may offer a different housing choice or tax profile. Compare actual homes and current quotes.
Does Tennessee have a state income tax?
Tennessee does not currently tax earned personal income. Ask a qualified tax professional how a move would affect wages, business income, investments, residency, and filing obligations.
Are Nashville property taxes low?
Property taxes vary by county, city, assessed value, and exemptions. Compare the actual tax record for each property rather than relying on a statewide ranking.
Should I rent before buying?
Renting can be reasonable when employment, timing, or location is unsettled. Buying may fit when you understand the region, expect to stay, and have enough cash for closing, reserves, and ownership surprises. The answer is personal, not automatic.
How far outside Nashville should I search?
Start with your real recurring destinations and maximum drive time. A map radius is less useful than route testing during your normal travel windows.
What should I do on a relocation visit?
Tour different property types, drive the same corridors at different times, check daily conveniences, meet a lender when useful, and leave with a ranked short list rather than trying to see everything.
Can my current Realtor refer me to a Middle Tennessee agent?
Yes. I regularly work with referring agents, keep communication clear, and protect the client relationship while handling the Tennessee search. See my referral partner information for the process.
About Harley Pope
Harley Pope is a Middle Tennessee Realtor with Pope Real Estate Group at The Baker Brokerage. As a lifelong Middle Tennessee local, he helps buyers and relocating households compare Nashville with surrounding communities through practical conversations about housing, land, commute, condition, and everyday life. His work is focused on helping clients make a confident decision without overselling a location or hiding the tradeoffs.
If you are comparing Tampa with Nashville, Harley and Victoria Pope can help you turn the cost question into a property-specific plan. Contact Pope Real Estate Group at The Baker Brokerage to compare areas, prepare a decision trip, or coordinate with your current Realtor. Call or text Harley at 931-629-4836.