Buying a Home in Nolensville, TN: Communities, Commutes and Housing Options
Buying a home in Nolensville, TN, starts with the specific address, the daily route and the kind of ownership you want. The town's newer subdivisions, established homes and edge-of-town properties ask different questions about lot size, HOA rules, construction, utilities and price. Compare current listings with the same monthly budget and test the route before letting a floor plan decide for you.
Last updated: September 25, 2026. Inventory, pricing and projects change; this is a decision guide rather than a live market report.
Local perspective: Harley Pope is a lifelong Middle Tennessee local and a Realtor with Pope Real Estate Group at The Baker Brokerage. Harley and Victoria Pope help buyers compare Middle Tennessee homes through the lens of everyday use.
Locate the property before evaluating the marketing label
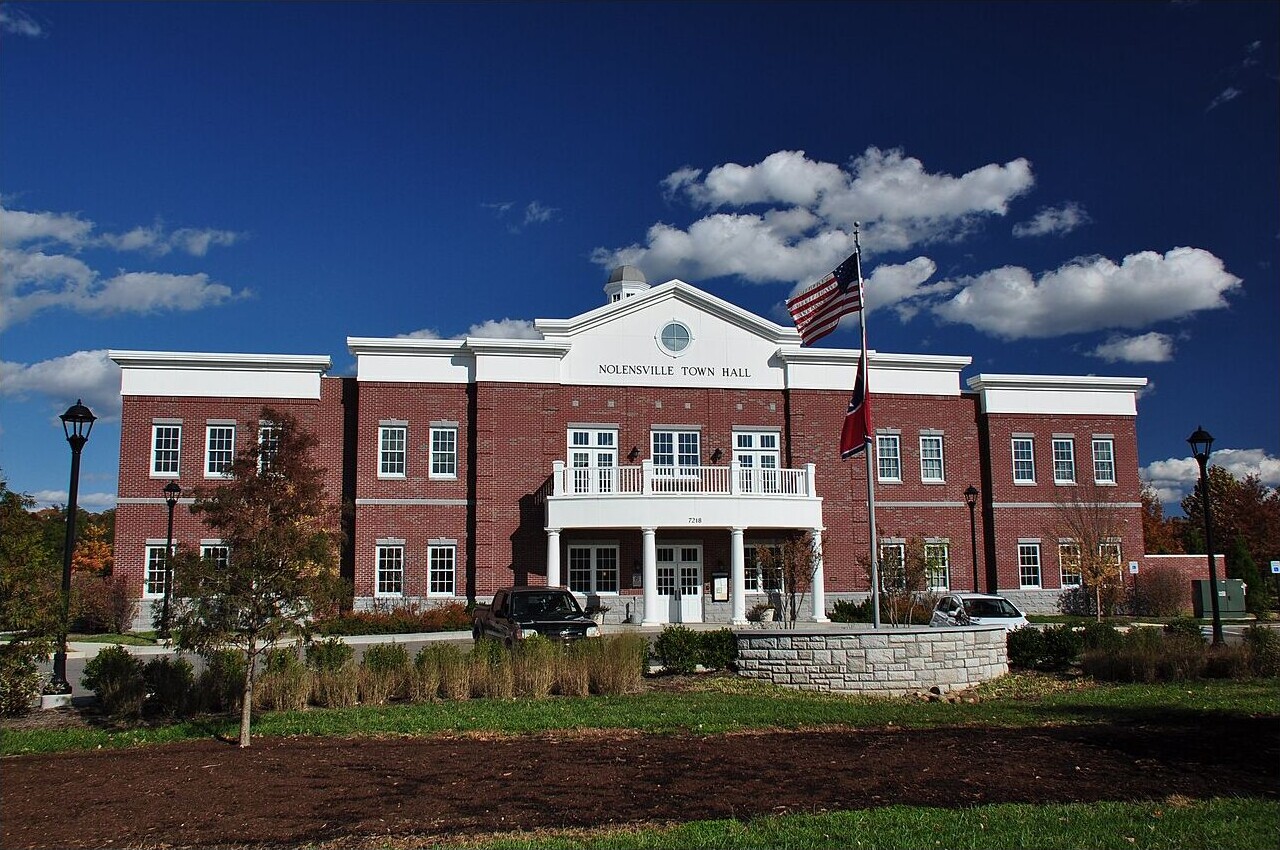
Nolensville is in Williamson County, but a search result labeled Nolensville is not enough to identify municipal boundaries, tax jurisdiction, utilities or the property's governing rules. Look up the parcel and confirm whether it is inside the town. The town publishes planning documents and a major thoroughfare plan, which can inform questions about its road network. Those plans are not a promise that every depicted improvement will happen on a particular timetable.
Map your own destinations. A commute toward Nashville, Franklin or another job center will feel different depending on the exact street, start time and the last part of the trip. Drive the likely route at comparable hours. If you work remotely, test the trips you still make several times a week. It is possible to buy too far from the life you lead even while rarely going to an office. A compelling house photo cannot answer the route question.
Stand outside the candidate home and imagine a regular evening. Where will you park? How does traffic move out of the street? Which errands can be combined and which demand a separate drive? Is the outdoor space actually usable for your plans? A location that works for one household may be inconvenient for another. The Tuesday Test turns a broad 'community feel' impression into a specific, repeatable decision.
Compare three housing paths
First, consider an established home where trees, street patterns and neighboring uses are visible now. Inspect the systems, drainage, additions and maintenance records. The age of a house is neither an automatic weakness nor an automatic source of character worth paying for. Identify the work you would need to do in the first year and price it with realistic quotes where possible.
Second, examine recently completed or new subdivision homes. These may deliver layouts with open living areas, additional work space or new equipment. Check the actual lot, orientation, grading, what the builder includes and what remains under construction nearby. A model home can show options that the base price excludes. Confirm finished square footage, appliance packages, landscaping, fencing and the delivery date in writing. Inspect the completed home even when it is new.
Third, evaluate a more individual property on a larger or less conventional lot, if such a listing meets your budget. It may offer privacy or room for a project but require a closer look at access, drainage, outbuildings, wastewater and maintenance. Do not treat 'more land' as a complete benefit. Measure the portion you can use for the activities you have in mind and the time it will take to care for it.
Each path needs its own comparable sales. A large older house with deferred maintenance and a smaller new house with HOA dues should not be compared solely by asking price per square foot. The meaningful comparison includes condition, location, floor-plan utility, lot and total cost of ownership.
Understand HOAs and new construction terms
Many buyers reasonably want to know what an HOA fee covers and what the rules permit. Request the declaration, current budget, insurance summary, meeting information and any known special assessment. Ask about fencing, parking, short-term rental rules if relevant, exterior changes and use of common areas. The details vary by association. A monthly fee may cover certain shared work while leaving the roof and yard to the owner. Confirm rather than guessing.
For a builder contract, read how design choices, inspections, financing contingencies, deposits and completion delays are handled. A builder's preferred-lender credit can be useful but compare the complete rate, points, closing costs and cash-to-close with an independent alternative. Determine whether the credit is tied to a closing date or another condition. A warranty should be read as a written remedy with exclusions and deadlines, not as a guarantee that nothing can go wrong.
Ask what is planned on adjoining land and what has actually been approved. The town's planning materials and meeting records can clarify the status of a specific proposal, but a concept drawing should never be sold to you as a certain future amenity or road. Even approved development can change. Base your purchase on the property and access you can verify today, then regard possible changes as scenarios to consider.
Price the whole home and location
Tell your lender the total monthly payment you can carry comfortably, including taxes, insurance and HOA dues. The Consumer Financial Protection Bureau's Loan Estimate guidance is useful when comparing those components. Keep money for moving, furnishings, inspections and unexpected first-year work. The purchase ceiling in a preapproval is a financing limit, not a recommendation for how much of your income to spend.
The Tennessee comptroller explains that residential property is assessed at 25 percent of appraised value for the tax calculation, followed by the applicable rate. Verify the exact parcel's Williamson County and municipal status and ask about the estimated bill on a completed new home. An existing owner's prior bill may be based on a different valuation or an unfinished parcel. Obtain an insurance quote, and compare that plus HOA and likely utilities across your shortlisted homes.
Put time on the same decision sheet. If one home costs less but requires a longer trip to your actual destinations, decide whether that trade fits your schedule. If another is closer but needs immediate updates, get repair estimates. One property can be a better purchase for your life even at a higher ask, provided the payment and condition make sense. Another can look attractive on paper and quietly absorb too much of your week.
Compare nearby communities honestly
Franklin, Brentwood and Thompson's Station can be useful comparisons for a Nolensville buyer, but they answer different location and housing questions. Spring Hill is another south-side search that crosses Williamson and Maury counties. Look at actual homes at one payment and similar bedroom utility, then compare the weekday route. A broad statement that one city gives more house for the money may collapse important differences in age, lot and commute.
Our Franklin versus Nolensville comparison explores the two markets, and the Franklin and Spring Hill buying guides can frame alternatives. A buyer whose work and routines are east of Franklin may prefer a Nolensville address even when another community offers a larger house. Someone seeking a different town center or wider property type search may make the opposite choice. Neither preference should be driven by an unsupported description of who lives in a place or by a school ranking; verify any school assignment directly for a property if that information matters to you.
If land is your priority, look beyond a square-acre figure. Review survey, boundaries, easements and restrictions. Where a home uses a septic system, obtain available state records and learn whether your planned use affects permitted capacity or the disposal field. Tennessee's environmental agency notes that modifications can require a permit. An apparently open corner may be reserved for wastewater. Confirm the intended project before paying for potential you cannot use.
Tour deliberately and negotiate on evidence
Choose one example of each property type you are seriously considering. Bring a consistent note sheet: payment, drive, usable rooms, yard, parking, HOA or land restrictions, systems and first-year work. Pause after the tour to compare what each would change about your actual routine. An extra bedroom may not compensate for a less useful living space; a smaller lot may free up the time you wanted. Separate emotional appeal from the things you can verify.
For a resale offer, review closed comparables and active competition rather than trusting an automated estimate. Consider condition and seller timing. An inspection period gives you the chance to understand repairs and decide whether to renegotiate or proceed under the contract terms. For new construction, compare the builder's incentives and delivery obligations with available completed homes. In either case, obtain insurance early and make sure financing terms match the property.
Do not waive important protections solely to win an offer without understanding the exposure. Your exact leverage changes with the listing and timing; a broad article cannot determine it. A strong offer is one that the seller can reasonably rely on and you can responsibly close. Keep the required documents, lender, inspector and title review aligned so a preventable surprise does not turn a good house into a bad transaction.
What could change your mind?
Before you commit, write down three reasons to buy and three conditions that would make you walk away. The first list might include a usable floor plan, a reliable route and a payment with room to spare. The second might include unresolved drainage, restrictive HOA rules or a builder finish that differs from the contract. This is not pessimism. It ensures you can judge new information consistently during the inspection and document review.
Visit at a second time of day if the setting is important to you. Check actual street traffic, sunlight and noise. If a future road or development is material, contact the town for its current status and keep the uncertainty visible in your decision. The home should work even if a hoped-for improvement takes longer than expected.
Check the parcel after the first showing
Once a home becomes a serious contender, verify the deed and plat, the association documents, the municipal boundary and available permit records. Ask the insurer about the exact house, not an average in the ZIP code. An hour spent on these records can reveal a fence restriction, an easement or an ownership expense that changes the ranking. The result may confirm your enthusiasm, which is just as valuable as finding a problem.
Match the floor plan to the phase of life you are in
Think beyond a room count. If you need a quiet work area, check where it sits relative to the kitchen and the street. If you expect frequent guests, assess how they would enter, park and use a bathroom. If stairs may become inconvenient, note where the main bedroom, laundry and daily living spaces are now. A flexible floor plan may be more valuable than a specialized room you would use only a few times a year.
Tour during the kind of light and activity level you expect on a weekday. A house with a spacious open main floor may carry sound in a way a photograph cannot show. A small separate room may solve that issue without increasing the budget. Measure furniture and storage. New-home marketing frequently emphasizes finished square footage, while the actual utility of a mudroom, pantry or garage can matter more to day-to-day ownership.
If you are choosing between a house that is ready now and one still being built, account for timing. Temporary lodging and two moves can have a cost. A completed house gives you a clearer inspection opportunity; a future completion may offer more selections. Put those differences beside the price and financing, then choose the process you can manage.
A home purchase also has a timing component. If you are selling another property, ask which closing must happen first and what dates the lender can support. If you choose a builder home, construction completion and financing deadlines may not line up with your sale. If you choose a resale, the seller may have a different possession need. Write a calendar for the earnest money, inspections, loan, appraisal, documents and move. The best house on paper may require a transaction structure that is too fragile for your circumstances.
Frequently Asked Questions
Are all Nolensville listings within town limits?
No. Verify the parcel's boundaries and jurisdiction with official records before assuming taxes, services or rules.
Are builder incentives always cheaper than other financing?
No. Compare Loan Estimates, rate, points, fees, lender credit and the final cash-to-close using the same loan assumptions.
How can I tell whether a neighborhood road project will happen?
Ask the town for the project's current approvals and funding or schedule status. A planning map is not a guaranteed construction date.
Can I fence or modify a new subdivision home's yard?
Check the actual HOA documents, plat, utility easements and local permit rules before assuming a specific improvement is permitted.
Should I choose the largest house my payment allows?
Only if its layout, location and upkeep genuinely serve you. Compare usable space and total ownership cost, not square footage alone.
About Harley Pope
Harley Pope is a Middle Tennessee Realtor with Pope Real Estate Group at The Baker Brokerage. He helps buyers compare homes across Nashville, Williamson County, Maury County, Dickson County and surrounding areas. Victoria Pope works with Harley on the team. Their aim is to connect the price and property documents with a real routine: the route, rooms, outdoor work and time a home will ask of its owner.
If Nolensville is on your list, Harley and Victoria Pope can compare current homes there with the nearby options that genuinely fit your route and budget. Contact Pope Real Estate Group at The Baker Brokerage to plan focused tours and property due diligence.